After You File: How the IRS Reviews Art Donations
The art market is entering a period of profound change. As Bloomberg recently reported, an estimated $1 trillion worth of art is expected to change hands over the next decade as an aging generation of collectors begins to transfer its collections. With this shift already underway, the article sounded a warning bell: there may soon be more art than the market can absorb.
For many collectors, donating to a museum or other qualified institution offers an attractive alternative to watching a work stumble at auction or languish in storage. Lifetime giving can provide meaningful tax benefits both for collectors and their heirs, including a charitable deduction and reducing estate exposure. It also allows donors to have a say in where their works will go and can spare families difficult decisions and disagreements that can arise when a collection is divided or sold.
But donating art is not as simple as handing a museum a painting and claiming a deduction. The rules governing charitable contributions are complex, with important substantiation and valuation requirements and a specialized IRS process for reviewing them.
The good news is that none of this needs to be mysterious. The IRS publishes detailed guidelines for noncash charitable contributions such as IRS Publication 561, Determining the Value of Donated Property and IRS Publication 1771, Charitable Contributions - Substantiation and Disclosure Requirements and maintains two separate bodies to review the accuracy of art valuations.
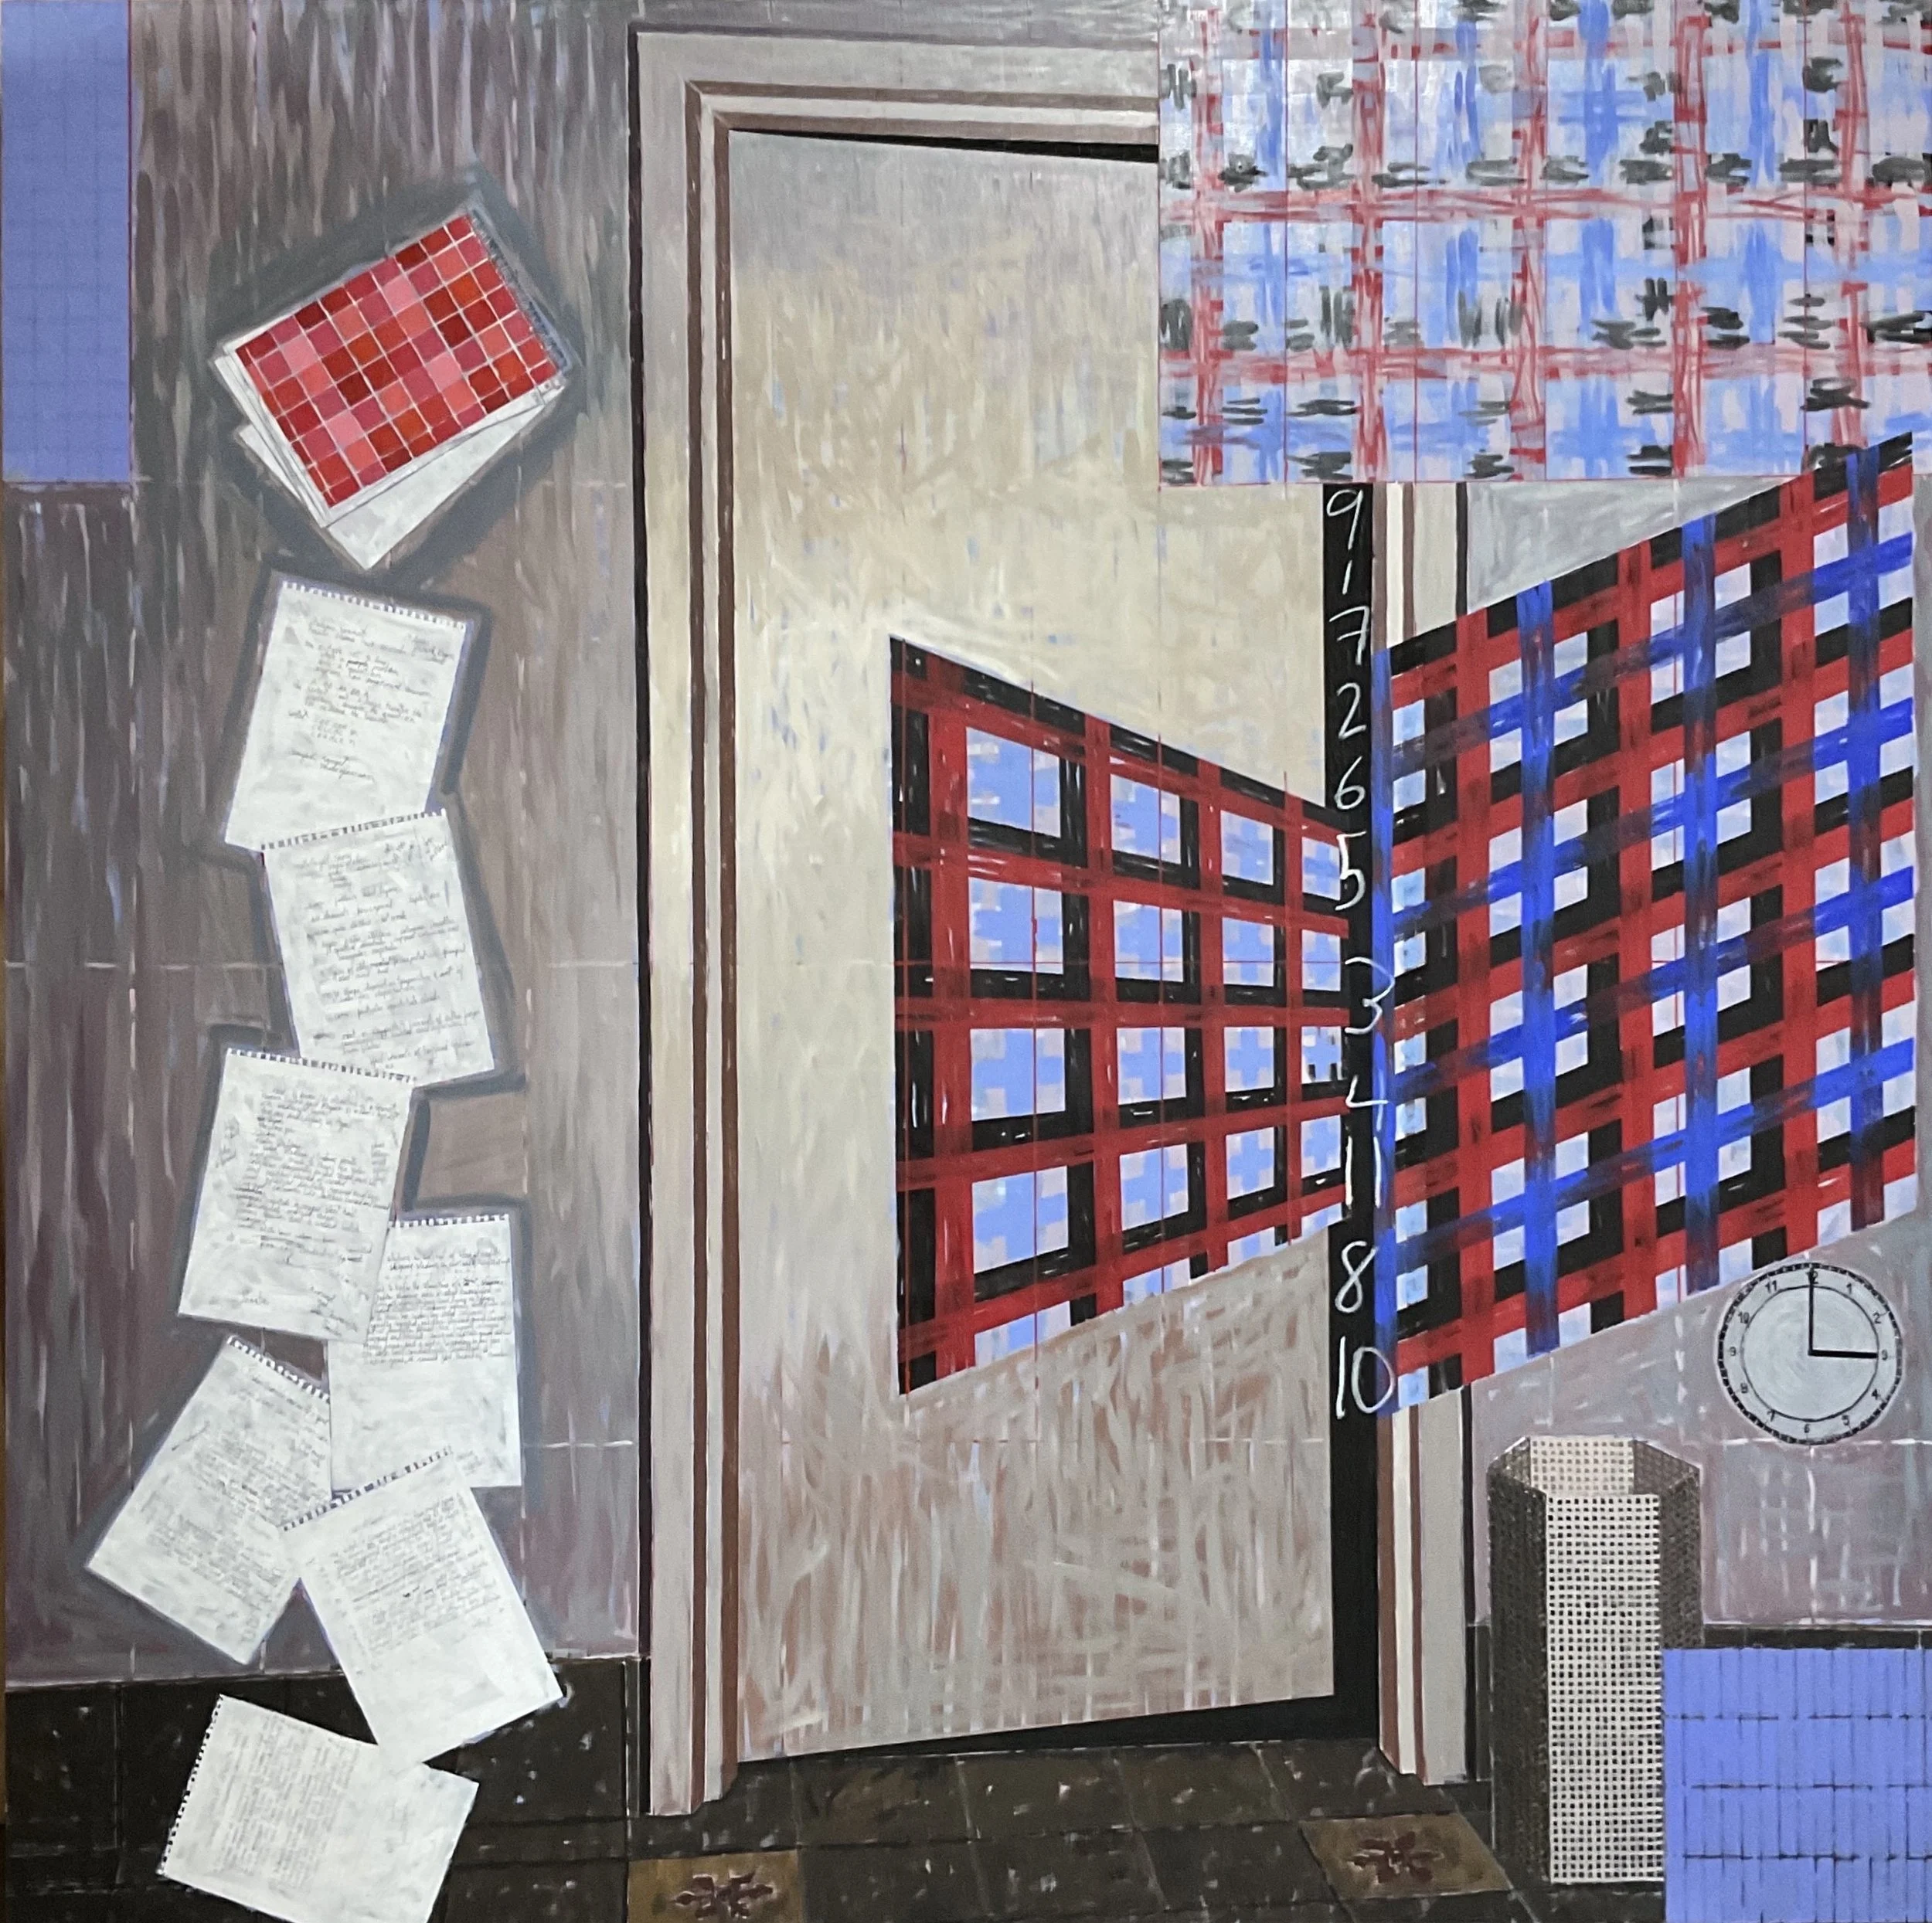
Jennifer Bartlett, Air: 24 Hours, Three P.M., 1991-1992. Oil on canvas, 84 x 84 in. The Museum of Fine Arts, Houston; Gift of Carol and John Finley.
Review of Deduction Claims
When reviewing an income tax return to ensure that the taxpayer is paying the appropriate amount of income, estate, or gift tax, the IRS may accept the claimed value of the donated property based on the information or appraisals submitted with the return, or it may make its own determination of the fair market value. In either case, the local IRS office may contact the taxpayer to request additional information or refer the file to an IRS appraiser or Art Appraisal Services (AAS). A referral to AAS is mandatory for art donations valued at $50,000 or more.
Art Appraisal Services
Art Appraisal Services (AAS) is an in-house team of professionally trained IRS appraisers that assists with valuation questions involving works of art and other personal property. AAS appraisers review the fair market value claimed in federal income, estate, and gift tax matters and respond to taxpayer requests for Statements of Value. They have training in appraisal methodology and the Uniform Standards of Professional Appraisal Practice (USPAP), along with education and experience in areas including fine art, decorative arts, antiques, collectibles, and other cultural property. Like a qualified appraiser that a taxpayer may hire to complete a qualified appraisal, AAS appraisers rely on publicly available information.
Art Advisory Panel
The IRS has another layer of review available for certain matters. AAS may refer a valuation to the Commissioner's Art Advisory Panel, established in 1968 to advise AAS on the valuation of works of art. The Panel consists of up to 25 recognized art experts such as gallery directors, museum curators, and scholars who serve without compensation. Generally, works with individual values above $150,000 are candidates for panel review, although the IRS has discretion over which works are referred.
The process is designed to be independent. Panel members review photographs and documentation supplied by the taxpayer, along with research conducted by AAS appraisers, without knowing the taxpayer or whether the valuation relates to a charitable contribution, estate, or gift. They consider factors including the work’s aesthetic quality and historical importance, as well as its fair market value. Given the extensive industry experience of the Panel members, the Panel is able to provide the IRS with unique insights.
The Panel reaches a consensus and provides an oral advisory opinion. It does not issue a written report. The Panel’s recommendations are strictly advisory. The final determination remains with AAS and only becomes the position of the IRS if AAS concurs. In fiscal years 2021, 2022, and 2023, AAS adopted the Panel's recommendations in full in 57%, 50%, and 63% of cases, respectively.
The Panel generally meets twice a year. Meetings are closed to protect taxpayer confidentiality, but the IRS publishes an Annual Summary Report each year describing the Panel's activities, procedures, panelists, and the works reviewed. These can be found on the IRS website.
Adjustments to the Claimed Value
The IRS's review is ultimately focused on whether the claimed fair market value is supportable. Comparable sales, the quality and importance of the specific work, its condition and provenance, the artist's market, and the broader state of the market at the valuation date can all matter.
AAS appraisers provide written reports or memoranda to the requesting IRS office. When they recommend an adjustment, the requesting IRS office shares a copy of the AAS report with the taxpayer, outlining the AAS appraiser’s final value determination, which may reference the Panel’s recommendations.
Taxpayers may request reconsideration of an adjusted claimed value by providing substantial new information or probative evidence. AAS may submit that information to the Panel for reconsideration at a subsequent meeting.
Advance IRS Review
Taxpayers do not necessarily have to wait until after filing a return to find out the IRS’s view of the valuation. They can request a Statement of Value from the IRS for advance review of certain art valuations before filing an income, estate, or gift tax return. The procedure generally applies to individual works of art appraised at $50,000 or more.
There is a fee for this service. As of 2026, the IRS lists a fee of $8,400 for one to three items and $800 for each additional item.
For a collector contemplating a particularly valuable gift, a Statement of Value can provide an additional level of certainty around the valuation before the return is filed. It does not, however, guarantee entitlement to a deduction or replace other substantiation requirements, such as Form 8283 or a CWA.
How Likely is an AAP Review and What are the Outcomes?
Despite the complexity of the substantiation and valuation requirements, relatively few art donations ultimately reach the Art Advisory Panel. Those that do, however, represent a significant share of the total dollar value of art donated each year.
In 2023, for example, the Panel reviewed 195 items across 37 taxpayer cases. By comparison, the IRS reported 76,258 art and collectible donations across 49,080 returns that year. The works selected for Panel review, however, represented exceptionally high values. The 195 items accounted for approximately $795.5 million of the $1.2 billion reported on taxpayers Schedule A that year, representing nearly 65% of total dollar value.
Even among these highly scrutinized works, the Panel recommended accepting the taxpayer’s claimed value more often than not. It accepted the claimed value of 103 items, or 53%, while recommending a decrease for 32% and an increase for 15%. Across all adjustments, the Panel recommended a net reduction of approximately $16.9 million, or about 2% of the aggregate claimed value.
Source: Internal Revenue Service, Art Appraisal Services
DISCLAIMER
This information should not be construed as investment advice and is subject to change. It is provided for informational purposes only and is not intended to be a specific offer by Museum Exchange or any affiliate to sell or provide.
Museum Exchange does not provide legal or tax advice. Please consult with your legal or tax advisor to properly determine your specific consequences from making a charitable gift through Museum Exchange.